

1:43
Learn the basics of bonds and their historical performance trends.
Understand the benefits and risks of various bond types.
Determine if investing in bonds makes sense for your financial goals.
Despite being a common investment vehicle, bonds can often be misunderstood, in our view. Many investors think bonds are a simple way to earn a safe return, but the reality can be quite different. In fact, bonds (often called fixed income) have many nuances, complexities and unique characteristics, which are important to understand. The better you know bonds, the better you'll be able to decide whether they have a place in your portfolio strategy.
As an investment manager, Fisher Investments doesn't focus on any one asset class—we manage a variety of strategies including stocks, bonds, cash and other securities. The optimal portfolio strategy for you will depend on your specific investment objectives, time horizon, cash flow requirements, outside income and assets and any restrictions or customizations you may have.
A bond is effectively a loan—a debt security issued by a company or government seeking capital. When you buy a bond as an investment, you own a contractual promise by the bond issuer to pay you interest (called a coupon payment) at scheduled times over the bond's life and repay you the principal amount borrowed at the end of the contract period (called the bond's maturity date). Unlike the much less certain returns of a stock investor, the bond issuer is required to pay investors according to the terms of the contract or indenture of the bond. For this reason, bonds generally have lower expected volatility risk than stocks—and historically, lower returns.
Companies issue bonds to raise capital for new plants and equipment, mergers and acquisitions, stock buybacks or other uses. Governments issue bonds to finance public works projects or other spending in excess of tax revenue. Unlike stocks, bonds are often traded over-the-counter through a network of dealers instead of on an exchange. Fixed Income Exchange Traded Funds (ETFs) are securities designed to track a specific bond market index, and are an exception to this rule as they are traded on an exchange.
When a company or a government issues bonds, it usually divides the bond issue into pieces worth $1,000 each so investors can buy them in units. This value, called the face value, is the amount the issuer promises to repay at the bond's maturity. For instance, if a company issues $1 million in bonds in units of $1,000, investors can buy as much—or as little—of the issue as they would like in lots of $1,000. Bond prices are often depicted as a percentage of face value. Generally, a bond trading at 100 means it would cost $1,000. A bond trading at 98.5 would cost $985.
A bond trading at its face value is said to be trading at par. An investor who buys a bond at par will have a return equal to the interest rate of the bond assuming they hold it until the maturity date, reinvest interest received at the same yield-to-maturity and, of course, the issuer is solvent throughout. A bond trading above face value is said to be trading at a premium. This is generally due to the bond having a coupon interest rate above those of comparable, newly issued securities. An investor who buys a bond at a premium and holds it to maturity will get a return somewhat less than the coupon interest rate. Therefore, the yield-to-maturity will be lower than the yield as the amount repaid at maturity will be less than the money invested in the bond. A bond bought at a discount is a bond trading below its face value, generally because it has an interest rate below newly issued comparable securities. Due to this, a buyer who purchases a discounted bond will have a yield-to-maturity exceeding the coupon interest rate.
Bond prices are not stagnant throughout their life; instead they generally move along with changes in interest rates. If interest rates rise, then bond prices fall and vice versa. Consider a hypothetical US Treasury bond paying 2% interest annually for 10 years. If interest rates rise to 3%, then the price of the 2% bond must decline to provide new purchasers with the now higher yield. Below is a graph showing the historical movement in 10-Year US Treasury Prices and 10-Year US Treasury Yields—they move in opposite directions.
Exhibit 1: 10-Year US Treasury Prices and Yields
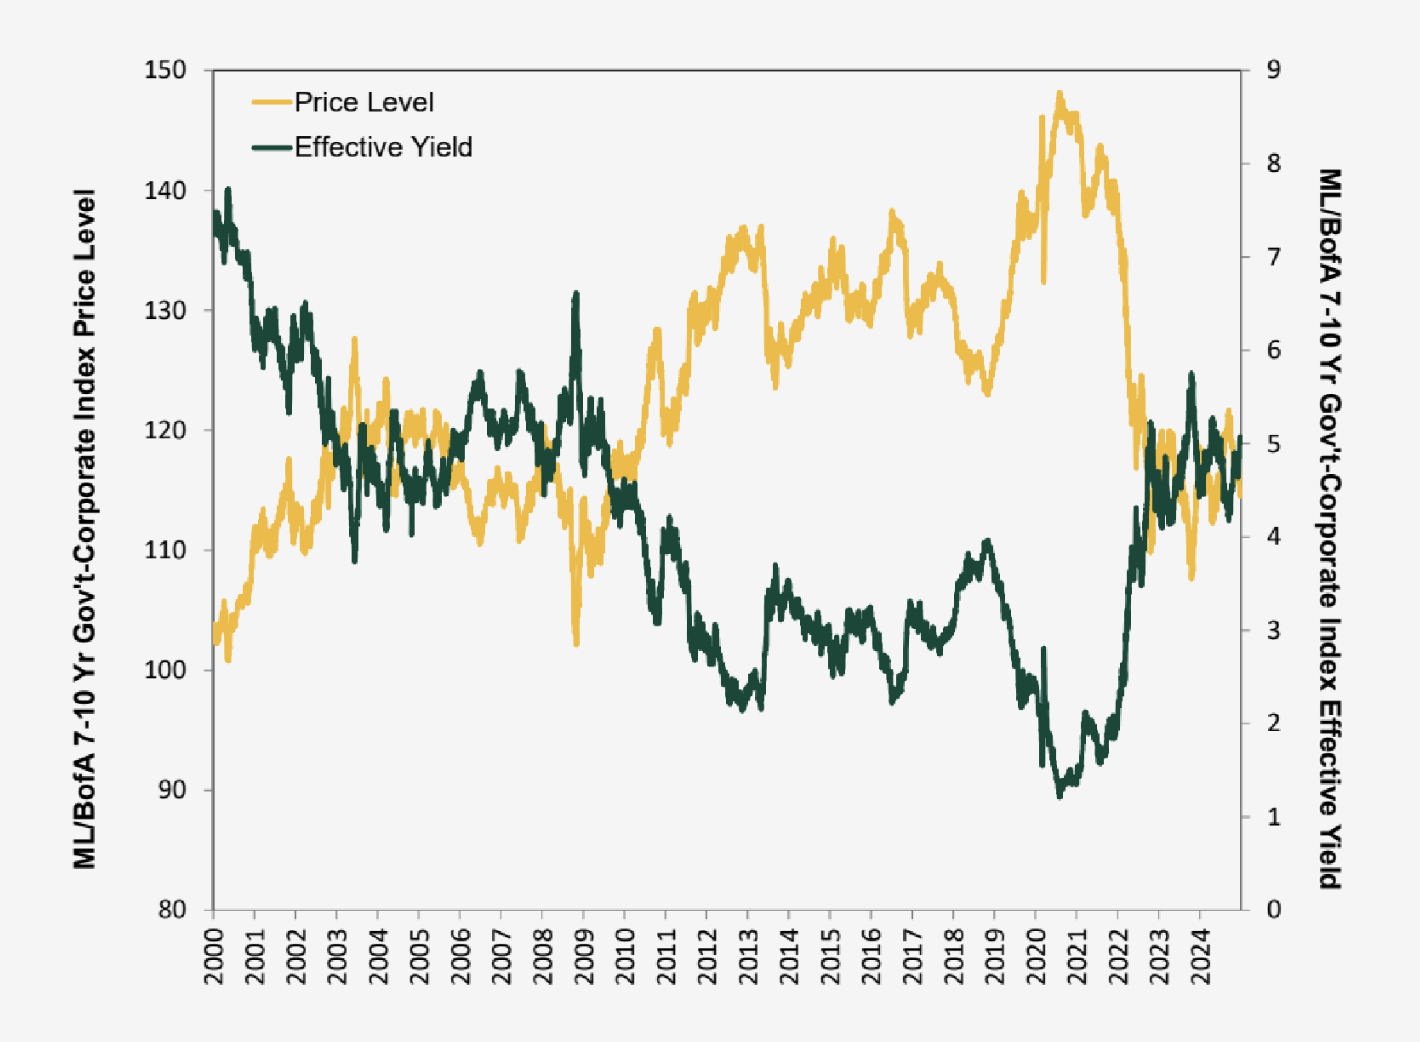
Source: FactSet, as of 5/13/2025. ICE BofA US Corporate & Government (7-10 Y), Price Return Index and Effective Yield from 1/3/1999 – 12/31/2024.
Changes to inflation expectations can impact yields as well. If investors expect inflation to increase over time, they will demand a higher yield to maintain their investment's purchasing power. In addition, changes (either real or perceived) in the issuer's ability to repay principal and/or interest can impact prices and interest rates as well. Greece's 2010-2013 debt crisis illustrates how this can occur. Prior to 2010, Greek government bond rates were at historically low levels. Then, as it became clear the country was in financial trouble and perhaps unable to meet its obligations, bond prices fell and rates rose—the market perceived Greek sovereign debt as riskier and demanded greater reward.
Many view bonds as a safe haven. While bonds often provide lower short-term volatility than stocks, volatility isn't the only risk to consider with an investment. Following are some of the risks you might consider when investing in bonds.
Interest Rate Risk
Since interest rates and bond prices have an inverse relationship, rising interest rates cause an investor's fixed income holdings to lose value. If investors sell these holdings before they mature, they can realize significant losses. As shown in Exhibit 2, interest rates fell dramatically leading up to 2020, but started to trend the opposite direction heading into 2021 and beyond.
Exhibit 2: Select US Bond Yields
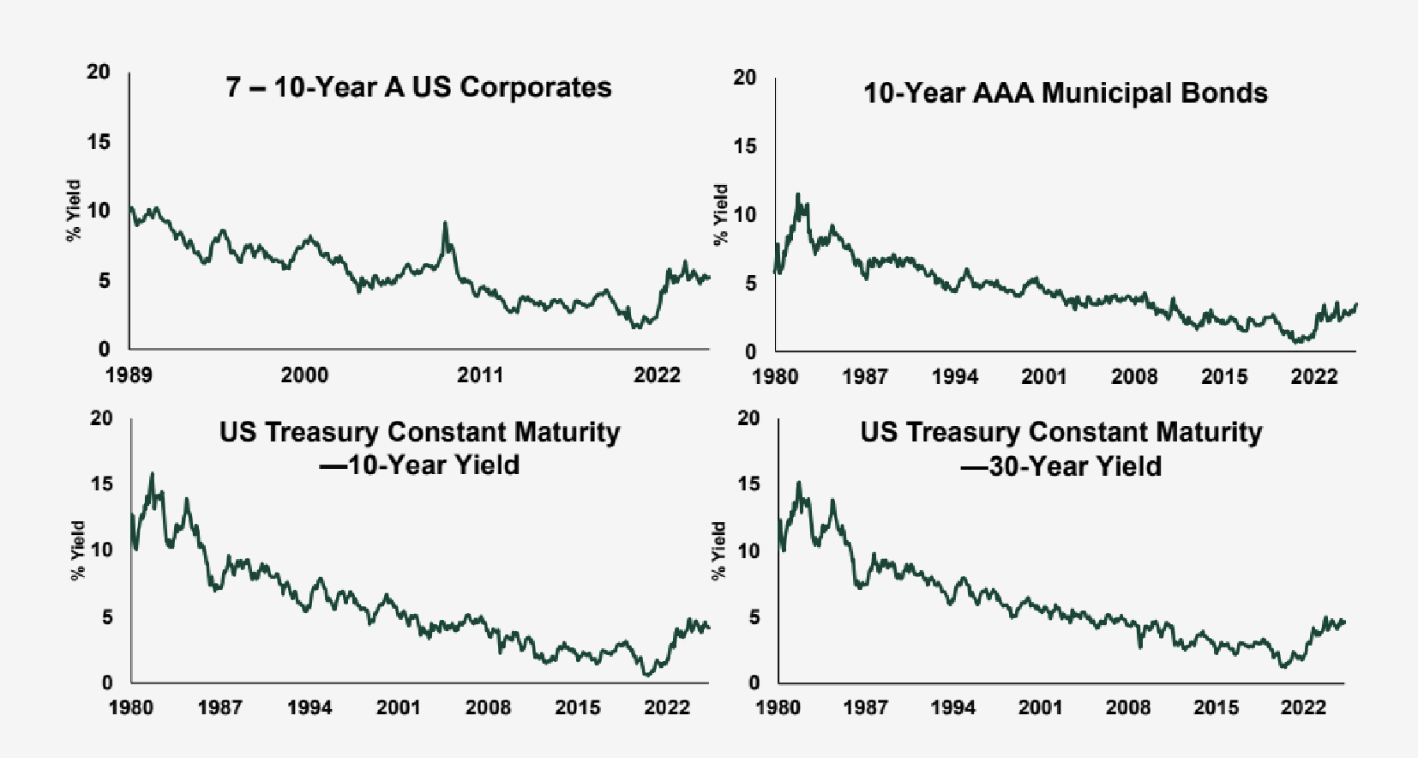
Top left source: Factset, as of 5/13/2025. 7-10 year US Corporate yields, monthly, 12/31/1988 - 4/30/2025. Top right source: Finaeon, as of 5/13/2025. 10-year AAA Municipal bonds, monthly, 12/31/1979 - 4/30/2025; Bottom left source: Factset, as of 5/13/2025. 10-year US Treasury constant maturity, monthly, 12/31/1979 - 4/30/2025; Bottom right source: Factset, as of 5/13/2025. 30-year US Treasury constant maturity, monthly, 12/31/1979 - 4/30/2025.
The higher interest rates rise, the worse the total return. Exhibit 3 shows current 10-year and 30-year US Treasury bonds and their expected total returns if interest rates, expressed as yield-to-maturity (YTM), rise by different amounts over the following 12 months.
Exhibit 3: Project Yield and Implied Total Return
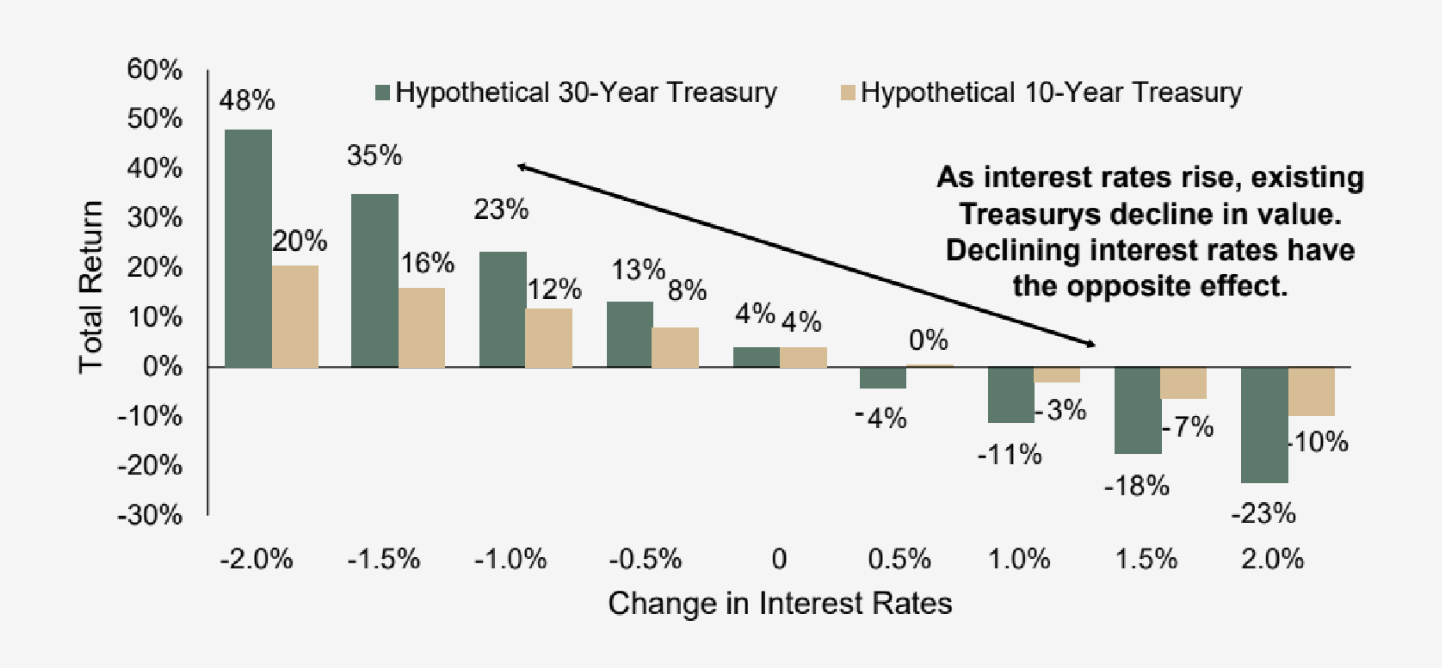
Source: Fisher Investments Research. Hypothetical 30-Year US Treasury, coupon 4%, face value $100, current price $100.
Investors who own high-coupon bonds from solvent issuers and plan to hold them to maturity might think they have a fool-proof investment, but even these bonds are subject to risk. Many corporate bonds are callable so the issuer can redeem them early at will. Companies will often do this when interest rates fall—it's better for their bottom line if they can replace expensive bonds with cheaper debt. As a result, not only do investors lose the coupon payment, but they lose the potential for a high realized gain if they decide to sell after interest rates fall.
Additionally, once debt matures or is redeemed, investors typically must buy another bond to replace it and continue providing that income stream. If interest rates have fallen, though, replacement can be difficult, and investors may have to settle for a lower yield—potentially impacting their income needs—or buy a riskier bond to keep their income stream intact.
Credit Risk
One determinant of a bond's interest rate is credit risk, or the risk of default. This is essentially the risk a bond issuer will fail to live up to an aspect of the contract. If investors perceive an issuer as less creditworthy, they will demand higher yields to compensate for the excess risk. This is similar to how banks charge higher loan rates to riskier borrowers.
Here are some factors that impact governments' and companies' credit risk:
Liquidity Risk
Investors who own individual bonds often run into a problem when they try to sell: Many bonds—primarily corporate and municipal bonds—aren't very liquid, which makes them difficult to price and trade.
Since stocks are traded every day, their market values are easy to assess. If you decide to sell a stock, it's almost a foregone conclusion your order will be filled at or near the current market price within seconds. If you decide to sell a thinly traded bond, however, there may be few purchasers, which would potentially require you to sell it at a discount. Worse, there may be no buyers, so you'd be in a tight spot if you had a near-term need for the proceeds.
Inflation Risk
Even if investors hold bonds to maturity in a rising interest rate environment, return isn't guaranteed. Most bonds aren't indexed to inflation; instead, their principal and coupon payments are set at issuance and remain the same to the bond's maturity. Investors may receive the face value coupon payment throughout the bond's lifespan, but over time even low inflation will erode the interest income's purchasing power. Similarly, investors may receive the full principal at maturity, but it will be worth less than when they purchased it.
Bond's real (inflation-adjusted) yield is one measure of inflation's impact. Exhibit 4 shows that real US Treasury yields have at times turned negative. In fact, even when nominal yields were lofty in the late 1970s and early 1980s, after factoring in inflation, yields were quite negative.
Exhibit 4: Real (Inflation-Adjusted) 10-Year Treasury Constant Maturity Yields
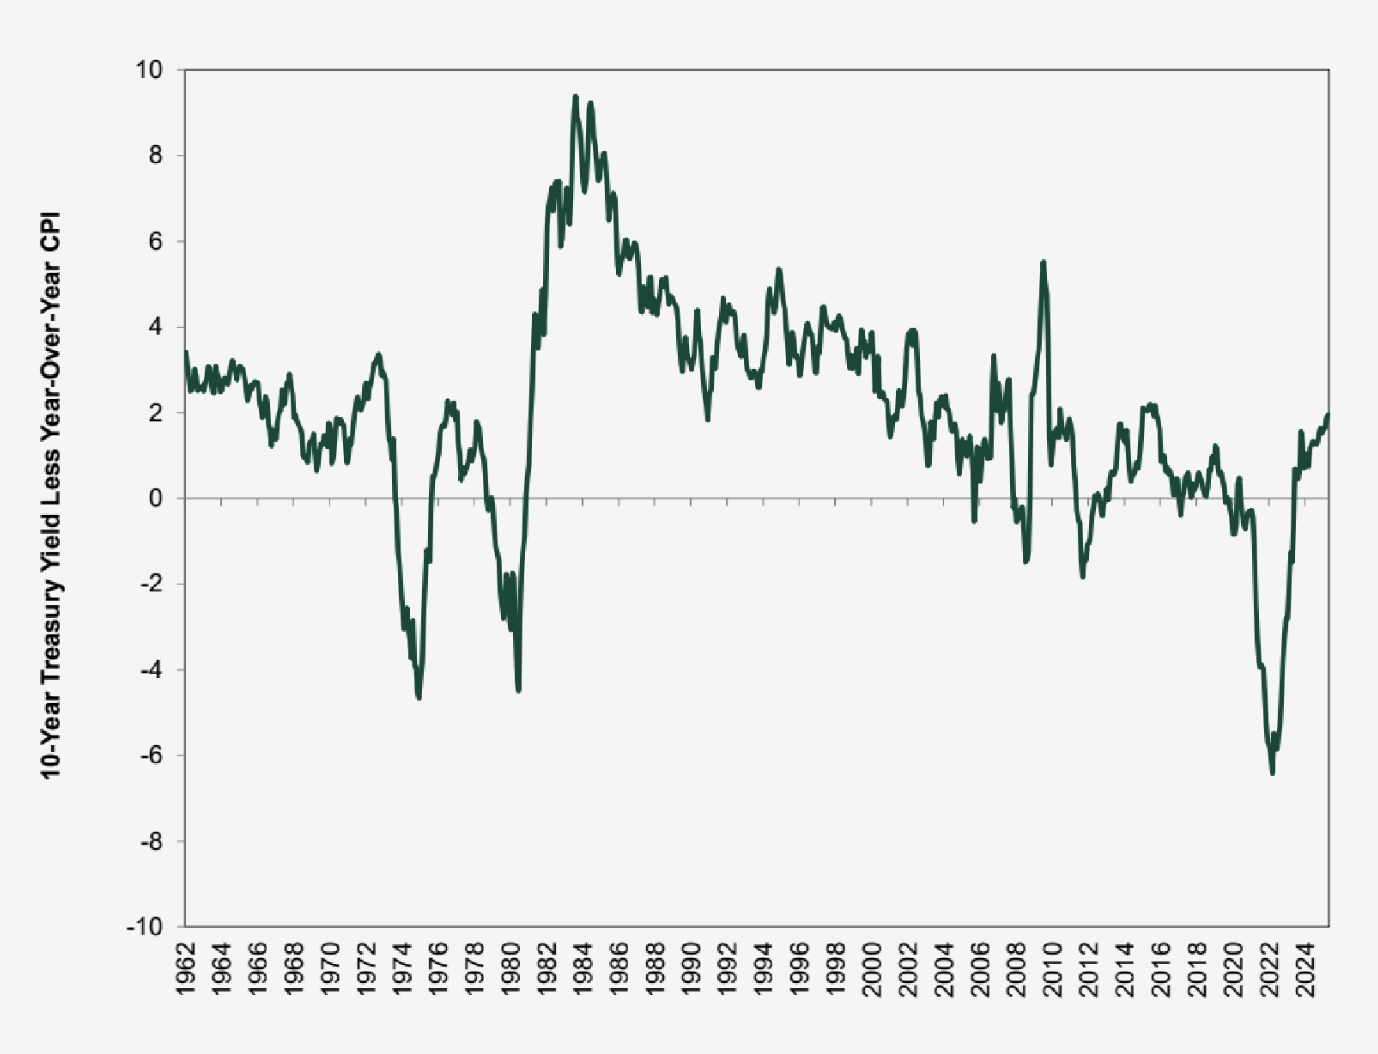
Source: Federal Reserve Bank of St. Louis, Yields from 1/1/1962 – 4/1/2025.
With nearly two million unique fixed income securities globally, differentiating bonds is crucial. There are many ways to break down the bond market—here are a few common ones with broad applicability.
Issuer
Details about a bond's issuer can help put bonds into broad buckets. For example, the issuer can be a corporation, municipality, government or government agency, each of which carries different risk and return characteristics. Below are some common subsets of each.
Government Bonds
Government bonds are those issued by a sovereign nation—US Treasurys, UK Gilts, Japanese Government Bonds (JGBs) and German Bunds are some examples. The highest quality sovereign bonds, like the aforementioned, are widely considered to carry little, if any, credit risk. Simply, the likelihood developed nations like these default on obligations is extremely low. Historical volatility also reflects this—Treasurys are among the least volatile investments available. The other side of the risk/return tradeoff is also true: Treasurys are among the lowest yielding investments available.
For American investors, Treasurys can carry some tax advantages. The interest is exempt from state and local income taxes, though investors owning bonds in a taxable account are subject to federal income taxes. Interest payments don't benefit from lower dividend or capital gains tax rates.
The Treasury market is further divided by maturity and interest type. Short-term Treasurys (called Treasury Bills, or T-bills) have a maturity of one year or less and don't pay interest. Rather, the bond is issued at a discount to the face value ($1,000), and when the bill matures, the gap between this discount and the $1,000 face value at maturity is the investor's return. This concept is called a zero-coupon bond. Treasurys with a maturity of 1 through 10 years are called Treasury Notes, or just Notes, and those with a maturity greater than 10 years are called bonds. Notes and bonds typically pay semi-annual interest.
While there's little credit risk in the US Treasury market, there can be inflation and interest rate risk. To specifically address inflation risk, the Treasury issues some bonds called TIPS—Treasury Inflation Protected Securities.
By design, TIPS adjust the principal amount of the bond by the inflation rate as measured by the Consumer Price Index (CPI). Though the coupon interest rate is lower than on a nominal bond, the interest payment changes with the CPI since it's based on the inflation-adjusted principal amount. The UK offers a similar option known as index-linked Gilts.
Municipals
Municipal bonds are issued by state and local governments and typically finance roads, building projects or other expenditures. There are two broad types: General obligation municipals and revenue bonds. General obligation bonds are backed by the local or state government's ability to tax generally. A revenue bond, by contrast, is backed by the specific revenues of the project the bond finance. Since revenue bonds are funded via a narrower income stream, the credit risk is considered higher.
Municipal bonds are typically rather low yielding on a nominal basis, but their tax benefits can be attractive to some investors. Generally, when an investor owns a municipal bond issued in their home state, it's exempt from federal, state and often local taxation. Municipal bonds from states you're not a resident of may be exempt from federal income tax, but state and local taxes typically apply. Bonds of territories like Puerto Rico are an exception—they're tax free at federal, state and local levels.
Given the tax benefits, municipals are most attractive to those with taxable investment accounts, as IRAs and Roth IRAs already have tax advantages.
Corporates
As the name implies, corporates are bonds issued by private businesses. Of the three broad issuer categories, corporate bonds generally carry the highest yields but they also tend to be more volatile.
An investor purchasing a corporate bond is lending a corporation money for a specified period of time. By contrast, an investor purchasing stock in a corporation is part owner of the business. Corporates can generally be broken down into two broad categories: High-yield (junk) corporates and investment-grade corporates.
High-yield bonds carry more credit risk (a greater likelihood of default). They, therefore, tend to carry higher interest rates and see greater volatility. In fact, high-yield bonds can often gyrate similarly to stocks. Investment-grade firms are more established and are generally considered to carry less credit risk so they pay less interest.
Corporates tend to be the highest yielding category of bonds as their price movements are not solely tied to movements in prevailing interest rates. Often, overall economic conditions and/or the company's financial health can impact prices. For example, during the 2008 financial panic, corporate bond prices fell sharply as markets priced in a recession ahead—a recession that would likely pressure many businesses' finances. The effect of this is the same as with any bond—when the price falls, the current yield rises. These rising yields are often seen as a measure of credit or default risk. Essentially, investors will compare corporate yields (either an index or a specific issue) to a very low credit risk bond yield—Treasury rates. The difference between the two is called a credit spread. Wider spreads mean more perceived risk, narrower means less.
Agency Bonds
Agency bonds are those issued by divisions of (or organizations sponsored by) the US Federal Government. Many have characteristics similar to Treasurys, as there's a presumption an Agency would be backed by the US Government in the event of financial trouble. But coupon interest rates can be somewhat higher as this backing is implicit, not explicit.

Get the complete guide.


